The Importance of Saving Money for the Future
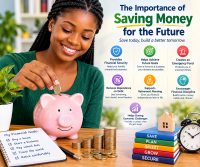
The Importance of Saving Money for the Future
By: Okunlola Christiana Omolola
Saving money is an important financial habit that helps people prepare for both expected and unexpected needs. Whether you are a student, employee, business owner, or retiree, developing a saving habit can provide greater financial security and peace of mind.
The Importance of Saving Money for the Future
1. Provides Financial Security
Saving gives you money to depend on when unexpected expenses arise, such as medical bills, repairs, or loss of income. It reduces the need to borrow money during difficult times.
2. Helps Achieve Future Goals
Savings can help you achieve important goals such as buying a house, starting a business, paying school fees, or purchasing a car. Having a clear savings plan makes these goals more achievable.
3. Creates an Emergency Fund
An emergency fund provides financial protection when unexpected situations occur. Ideally, people should gradually build enough savings to cover essential expenses for several months.
4. Reduces Dependence on Debt
People who have savings are less likely to rely heavily on loans or credit cards when they face financial challenges. This can help reduce interest payments and long-term debt.
5. Supports Retirement Planning
Saving throughout your working years can provide additional financial support during retirement. Starting early gives your money more time to grow through appropriate investments.
6. Encourages Financial Discipline
Regular saving teaches people to control unnecessary spending and make thoughtful financial decisions. Even small amounts saved consistently can develop a strong money-management habit.
7. Helps During Economic Challenges
Inflation, job loss, rising living costs, and other economic difficulties can affect household finances. Having savings can provide a financial cushion during challenging periods.
Conclusion
Saving money is not only about putting money aside; it is about preparing for a more secure future. By setting financial goals, reducing unnecessary spending, and saving consistently, people can become better prepared for emergencies and future opportunities.